Business Insurance Built Around Your Industry
We're a veteran-owned independent agency in Monticello, MN, and we match commercial coverage to the risks of your industry. Then we compare carriers, so a contractor, a nonprofit, and a professional office each get the policy their work actually calls for.
Commercial insurance is our primary focus
Coverage compared across multiple carriers
A consultation before every recommendation
30+ years of combined team experience
Industry-Specific Business Insurance for the Northwest Metro
No two businesses carry the same risk. A remodeling crew worries about job-site injuries and certificates. A consulting firm worries about a client claiming bad advice. A nonprofit board worries about personal liability. We start every commercial relationship by learning how your business operates, then build coverage around the risks that come with your industry.
Below are the types of businesses we work with most often across Monticello, Elk River, Buffalo, St. Michael, Albertville, Rogers, and the surrounding area.
Contractors and Tradespeople
Contractors face job-site injuries, damage to client property, stolen tools, and a steady stream of certificate requests. Coverage has to work together across your crew, trucks, equipment, and contracts.
- General liability with completed-operations coverage and additional-insured endorsements
- Workers' compensation with accurate class codes for each role
- Commercial auto for work trucks, vans, and trailers
- Tools and equipment coverage on and off the job site
- Builder's risk for projects under construction
- License, bid, and performance bonds
Our
contractor insurance page explains how these coverages fit together for builders and trades.
Professional Service Firms
Consultants, accountants, real estate offices, design firms, and other professionals are paid for their judgment. That means the biggest risk is often a client claiming a mistake cost them money, not a slip-and-fall.
- Professional liability (errors and omissions) for claims tied to your advice or services
- General liability for office visitors and client meetings
- Commercial property for your office, equipment, and business interruption
- Workers' compensation as your team grows
Learn more about professional liability insurance, including claims-made coverage and contract requirements.
Nonprofit Organizations
Nonprofits balance tight budgets, volunteers, events, and board members who want to serve without putting their personal assets at risk. Coverage needs to fit the mission and meet grant or funder requirements.
- Directors and officers (D&O) coverage for board decisions
- General liability for programs, facilities, and volunteers
- Special event coverage for fundraisers and community events
- Commercial property for buildings, equipment, and donated items
- Workers' compensation for paid staff
Our directors and officers insurance page explains D&O coverage for nonprofit boards, and our
special event insurance page covers fundraisers and community events.
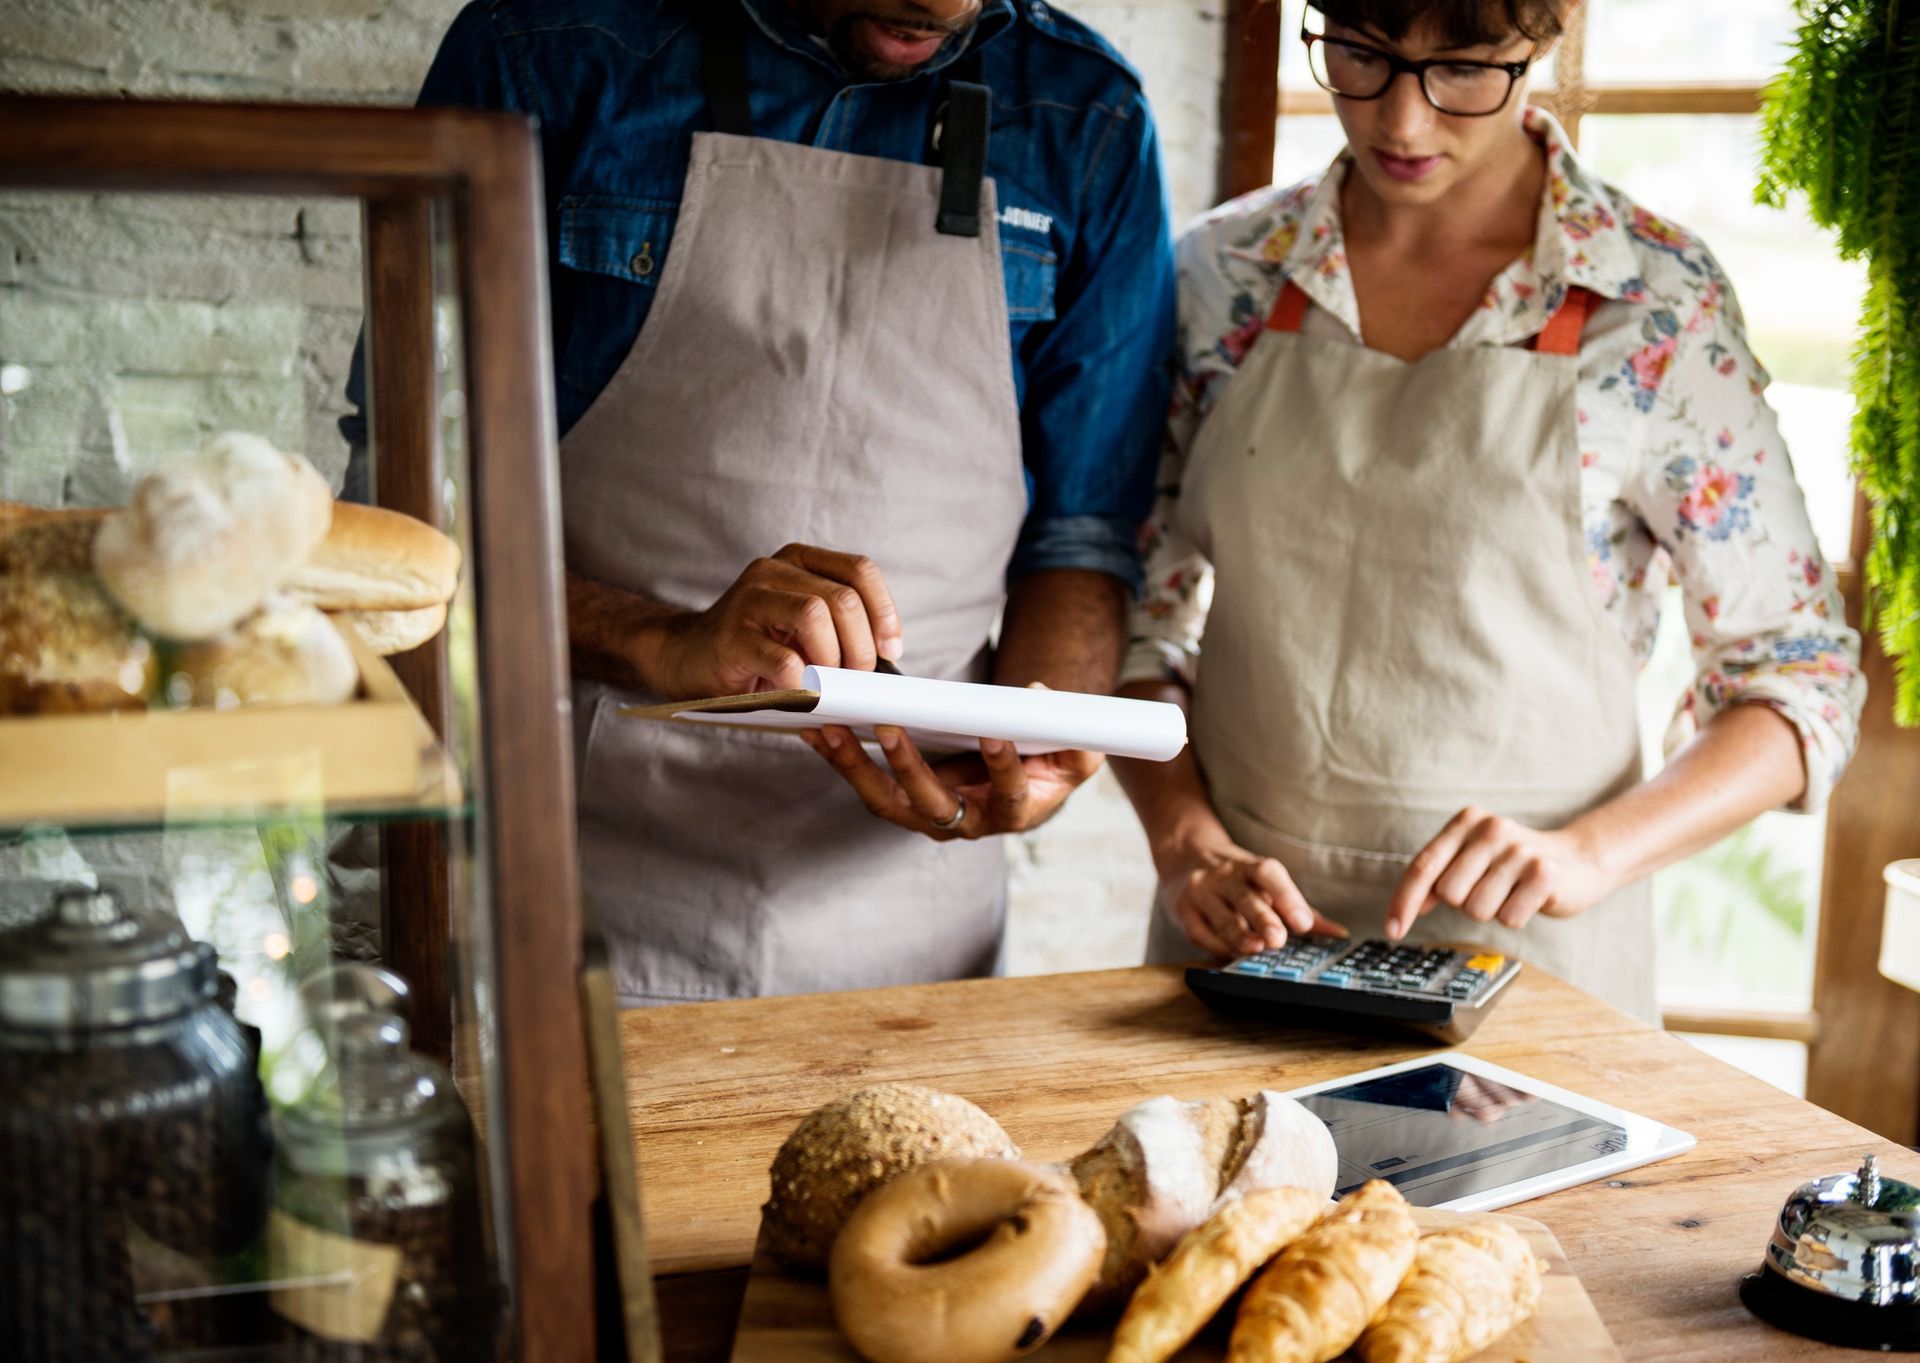
Retail, Restaurant, and Main Street Businesses
Storefronts and service businesses deal with customer foot traffic, inventory, leases, and the risk of closing temporarily after a loss.
- General liability for customer injuries and property damage
- Commercial property for inventory, fixtures, and equipment
- Business interruption to help replace lost income after a covered loss
- Workers' compensation for employees
- Commercial auto for delivery or service vehicles
- Certificates for landlords and shopping centers
Our
commercial property insurance page covers building, inventory, and business interruption in more detail.
Property Owners and Real Estate Investors
Owning property comes with risks that standard policies don't always handle, especially when a building sits empty, hosts short-term guests, or is under renovation.
- Commercial property and liability for occupied buildings
- Vacant property coverage placed with specialty carriers
- Short-term rental coverage for Airbnb and VRBO properties
- Builder's risk for renovations and new construction
Learn more about vacant property insurance, short-term rental insurance, and builder's risk insurance.
Growing Businesses With Employees and Vehicles
As you hire and add vehicles, your insurance has to keep up. Workers' comp and commercial auto are usually the first coverages to need a fresh look.
- Workers' compensation from your first employee, as Minnesota requires
- Commercial auto for owned vehicles, plus hired and non-owned auto
- Higher liability limits as contracts get bigger
- Regular coverage reviews as payroll and operations change
Why Local Businesses Trust Us With Their Coverage
Commercial insurance is our primary focus, not an add-on to personal lines.
We start with a consultation about your operations before we recommend anything.
We're independent, so we compare carriers whose appetite fits your industry.
We're veteran-owned, with more than 30 years of combined insurance experience.
We handle certificates, policy changes, and renewals through a local team that knows your account.
We meet face-to-face in Monticello, and in Ham Lake by appointment.
Customer testimonials on Google
A Local Commercial Insurance Agency Near You
Our office is at 261 East Broadway in downtown Monticello, serving businesses across Wright County, Sherburne County, and the northwest Twin Cities.
5 Star Insurance Protectors
261 East Broadway, Monticello, MN 55362
(763) 432-2645
Monday–Thursday 8:30am–4:30pm, Friday 9:00am–4:00pm
Ham Lake satellite office: Meetings by Appointment Only
Questions Business Owners Ask About Industry Coverage
Do different industries need different business insurance?
Yes. Most businesses need general liability, and Minnesota requires workers' comp once you have employees, but the rest depends on your industry. Contractors often need bonds and builder's risk, professional firms need E&O, and nonprofits often need D&O.
What insurance does a nonprofit need in Minnesota?
Most nonprofits start with general liability, directors and officers coverage, and property coverage for their facilities and equipment. Workers' comp is required for paid employees, and special event coverage helps with fundraisers.
What insurance do consultants and professional firms need?
Professional liability (errors and omissions) is usually the most important coverage, since it addresses claims that your advice or services caused financial harm. General liability, property, and workers' comp round out most policies.
My industry isn't listed. Can you still help?
Very likely. These are the businesses we work with most often, but we write commercial coverage for many other types of operations. Schedule a consultation and we'll talk through your business.
Let's Talk About Your Business
Every industry has its own risks, and the best way to cover yours is a conversation about how your business actually runs. Tell us about your operation and we'll schedule a time to review your coverage and compare carriers. You can also see every coverage we offer on our
commercial insurance page.
Prefer to talk now? Call us at
(763) 432-2645.